

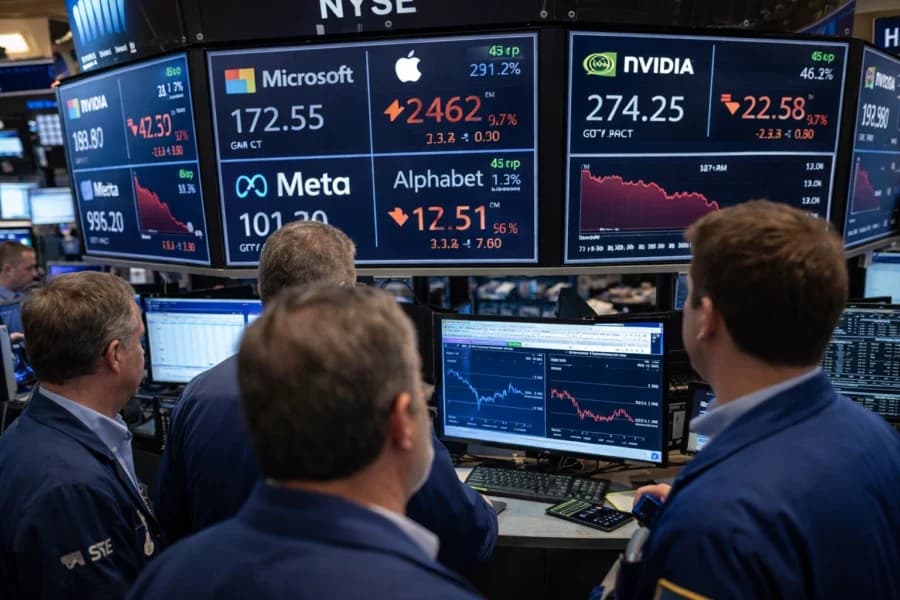
It was bound to happen. When an astronomical $2.3 trillion in market capitalization evaporated from the tech sector's elite (the so-called Magnificent Seven) in June and July 2026, Wall Street analysts finally began to speak of a sobering reality check. For three years, stock markets fed greedily on the promise of an imminent artificial intelligence revolution. Nvidia’s valuation soared into orbit, while Microsoft, Google, and Apple raced to show off successive iterations of Copilots and Geminis. However, by mid-2026, investors finally asked a basic, uncomfortable question: where are the actual profits from these trillion-dollar capital expenditures?
You can build market cap on promises and slideshows, but in the long run, the market always returns to fundamentals: revenue and margins. AI has proven to be incredibly expensive to sustain.
The primary driver of the massive sell-off was growing doubt over the Return on Investment (ROI) of AI infrastructure. Constructing data centers packed with custom graphics accelerators from Nvidia has cost hundreds of billions of dollars. Yet, demand for advanced AI services from corporate and individual clients has failed to grow at a pace that justifies these investments. Instead of a productivity revolution, companies ended up with costly chatbot deployments that consume massive amounts of energy without delivering proportionate gains. The initial dip in Nvidia and Microsoft shares proved that Wall Street’s patience has limits.
Geopolitics and Energy: The Physical Bottlenecks of Silicon
Physical constraints also emerged as major bottlenecks. Cloud computing requires more than just silicon; it requires electricity. In 2026, data center energy consumption spiked to such an extent that Microsoft was forced to sign power purchase agreements with experimental fusion startups and decommissioned nuclear facilities. Operating costs are rising faster than software margins, dragging down corporate balance sheets. Geopolitical tensions around Taiwan add further risk – any disruption to TSMC’s production lines would immediately paralyze the entire AI supply chain.
Nvidia faces additional scrutiny over its controversial "revenue-sharing" licensing models. The chipmaker is attempting to collect fees not just on physical hardware sales, but is also demanding a percentage of the profits generated by the cloud providers running its GPUs. This move has drawn fierce pushback from clients and attracted antitrust regulators in both the US and EU, who have launched investigations into Nvidia’s market dominance.
What Lies Ahead for the Remainder of 2026?
The current market correction does not signal the death of AI. Rather, it represents a transition from uncritical hype to rational development. Hundreds of startups offering thin wrappers around third-party APIs will be swept away. The survivors will be those who can demonstrate tangible utility and optimize infrastructure costs. Google and Apple, which took a more measured approach to the AI frenzy, may emerge stronger by focusing on local, on-device processing that avoids massive cloud compute costs.
For PC enthusiasts and gamers, this Wall Street downturn could yield unexpected benefits. A slowdown in GPU acquisition by cloud hyperscalers will free up silicon wafer allocations at TSMC. This change should finally stabilize and potentially lower the retail prices of consumer graphics cards, which have been inflated for two years due to prioritized AI production.
The lesson of mid-2026 is clear: no technology, no matter how promising, can escape the laws of economics. Replacing skilled workers with unpolished models in a bid to cut costs has resulted in declining service quality, a compromise consumers were quick to reject. Big Tech must now prove that AI can generate sustainable profits without a constant influx of speculative venture capital.

Comments
Discussion
Join the conversation around this story.
Join the discussion
Sign in to comment and reply to other readers.
Sign inNo comments yet
Start the discussion first.